

Gerald - Cash Advance
4.4

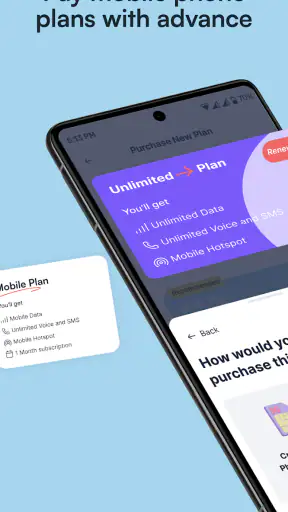
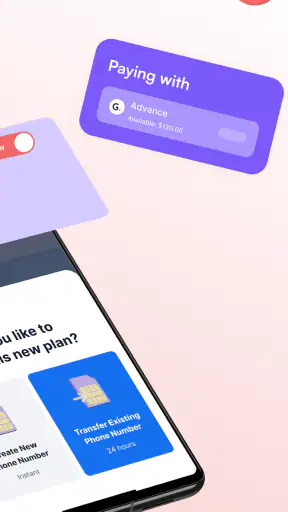
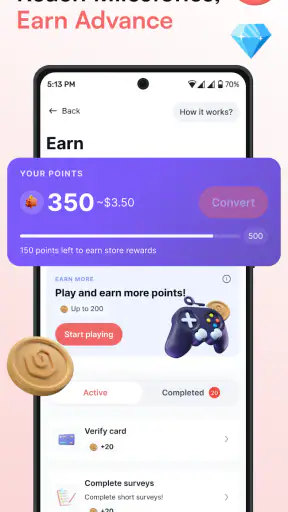
When an unexpected bill lands between paydays, the most useful thing is often not a large financial product but a quick, clearly explained bridge. That is the role I see for Gerald Cash Advance: a free finance app from Gerald Technologies, Inc. that focuses on getting cash to users without a credit check or interest. I found its appeal easy to understand, but I also think it works best when treated as a short-term tool rather than a replacement for regular budgeting.
The app is aimed at adults and carries an Everyone content rating, which makes its presentation approachable rather than intimidating. It has reached over 500 thousand installs and holds a 4.4 average from around 10 thousand ratings, so it is not an obscure experiment. The current Android release is version 69.0.9, and it runs on Android 7.0 or later. Those details matter if you are using an older phone, because compatibility is broader than with many newer finance apps.
What the cash advance capability really changes
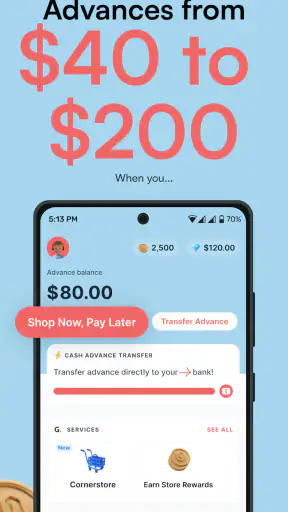
The central promise is straightforward: request access to cash without relying on a traditional credit check and without paying interest on the advance. In practical terms, that can make the app feel less like a loan application and more like a temporary cash-flow option. I would describe the benefit as reduced friction, not free money. You still need to think about how the amount will fit into your next financial cycle.
That distinction is important. A credit card may give you more flexibility, but it can also introduce interest charges if you carry a balance. A bank overdraft may be familiar, yet it can create its own costs or account complications. A conventional personal loan is usually excessive for a small, urgent expense. Gerald sits in a narrower space: it is designed for the moment when the problem is timing rather than a long-term shortage.
I particularly like the way the no-interest positioning changes the decision process. Instead of calculating an interest rate, I would focus on the repayment timing, the amount I actually need, and whether taking the advance solves a genuine short gap. That makes the app easier to evaluate than many borrowing products, although it does not remove the need to read every screen carefully before accepting anything.
The most useful mental model is to treat an advance as money arriving early, not as extra income. If I needed a modest amount to cover an essential purchase and knew that my next incoming payment could absorb the repayment, the feature would make sense. If I needed repeated advances to cover ordinary monthly expenses, I would see that as a warning that the underlying budget needs attention.
Using it for a real everyday problem
Imagine a utility payment is due before payday, while the money for that bill is already expected but temporarily unavailable. In that situation, an advance could help prevent the immediate problem from becoming a late payment. I would first calculate the exact shortfall rather than requesting the largest amount available. That small habit reduces the chance of turning a temporary gap into a larger repayment burden.
Another realistic use is an urgent household purchase, such as replacing an essential item when waiting several days is not practical. Here, the app may be more suitable than putting the expense on a high-cost credit balance. The important condition is that the purchase must be necessary and the repayment plan must be realistic. Convenience should not become a reason to borrow for impulse spending.
I would not use it for entertainment, speculative purchases, or a recurring subscription that I cannot normally afford. Those expenses do not solve a temporary timing issue. They simply move the same problem forward. The strongest use case is a defined, short-lived gap with a known source of repayment.
How the experience fits into a normal financial routine
Because this is a finance app, the quality of the experience depends on more than the headline capability. I would approach the setup with the same care I use for any service involving personal finances: check the identity and account details I am entering, review the requested amount, and read the repayment information before confirming. A fast screen flow is useful only when each step is understandable.
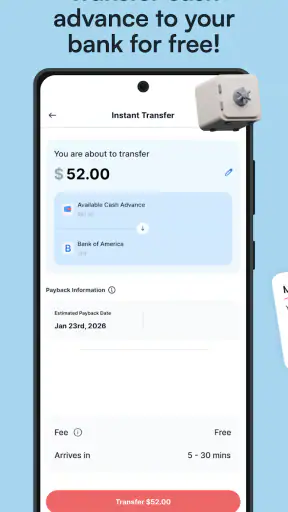
The app’s free price removes one obvious barrier to trying it. Still, “free” should not be interpreted as “without responsibility.” The advance itself is a financial commitment, even when interest is not charged. I would take a screenshot or note of the repayment date and amount for my own records, then make sure the money needed for repayment will remain available.
One practical tip is to separate the decision into two questions. First, do I need the cash for an essential short-term reason? Second, can I repay it without immediately needing another advance? Answering the second question honestly is more valuable than focusing only on how quickly the first request might be completed.
A second useful habit is to open the app before an emergency occurs and become familiar with its language and navigation. Financial stress makes unfamiliar screens harder to interpret. Knowing where the request details, account information, and repayment information appear can help prevent rushed decisions later. I would not wait until a bill is already overdue to learn how the app works.
A third tip is to compare the requested amount with the actual bill rather than rounding upward for comfort. If the shortfall is small, borrowing extra creates no benefit unless there is a clearly planned use for it. The no-interest feature may make the amount feel harmless, but repayment still affects the next pay cycle.
What I would check before confirming an advance
I would review the total amount involved, when repayment is expected, and whether the transaction fits my upcoming obligations. I would also check that the connected financial details are correct and that I have enough room in my account for normal bills after repayment. These checks are simple, but they are the difference between using a cash advance as a bridge and using it as a recurring patch.
I would also pay attention to wording that explains eligibility, delivery, or account requirements. The phrase “no credit check” does not mean every user receives every request or that no other conditions apply. It describes one part of the experience, not a promise that every situation will produce the same result. Reading the actual in-app terms is therefore more useful than relying on the short store summary alone.
The app is free to install, but I would still avoid making a decision based only on the word “free.” The relevant question is the complete financial effect of the advance. If any screen presents a charge, optional service, timing difference, or other condition, I would want that understood before proceeding. A careful review of the confirmation page is essential in any borrowing workflow.
For privacy-conscious users, the same principle applies to permissions and connected accounts: read what the app asks for and provide only what is needed for the service you intend to use. I would be especially cautious about installing it on a shared device or leaving financial notifications visible, since the phone itself can become part of the privacy risk.
The best situation for Gerald
In my view, Gerald is strongest for someone with predictable income who occasionally experiences a mismatch between the day a bill is due and the day money arrives. That person is not looking for a large loan, a rewards program, or a complex investment dashboard. They need a focused way to handle a short cash-flow interruption without adding interest to the situation.
It can also suit someone who wants to avoid using a credit card for a small essential expense. The absence of a credit check may be meaningful for users who are building or repairing their credit history, because the decision is not centered on a conventional credit-score review. However, I would not assume that using the app improves a credit profile. Its value is access to a temporary advance, not credit-building.
Consider a worker paid on a regular schedule whose phone bill is due a few days early. If the amount is already reserved in the next paycheck, an advance could prevent the worker from using an overdraft or carrying a card balance. I would still recommend requesting only the amount needed and setting a reminder for the repayment date. The app helps with timing; it cannot make the bill disappear.
This is also where Gerald compares favorably with borrowing from friends or family. Some people prefer a private, self-managed option rather than explaining a shortfall to someone they know. The trade-off is that a personal relationship may offer more flexibility, while an app provides a more formal process. Which is better depends on the user’s circumstances and comfort level.
Where another option may be better
If I needed money for a major repair, tuition, moving costs, or several months of expenses, I would not choose a cash advance as my main solution. A larger need calls for a broader plan, such as negotiating the bill, using savings, speaking with a bank, or seeking qualified financial advice. A small advance can be useful precisely because the problem is small and temporary; stretching it beyond that role is risky.
A credit card may be the better choice when a purchase needs strong consumer protections or when the user can pay the balance in full and already understands the card’s terms. A savings account is better whenever the expense can wait. An employer-based early-pay option may also suit someone whose workplace offers one and whose repayment structure is clearer to them. Gerald is not automatically the cheapest or safest answer simply because it avoids interest.
I would also skip it if my income is irregular and I cannot identify a dependable repayment source. The absence of a credit check may make access feel easier, but easy access can be uncomfortable when the next payment is uncertain. In that case, requesting an advance could shift stress from today to the next uncertain date.
The trade-offs that are easy to overlook
The first trade-off is simplicity versus context. Gerald concentrates on the immediate cash need, which is helpful when a user wants a direct solution. It is less suitable for someone who wants a complete financial planning system with detailed spending analysis, long-term savings tools, or investment guidance. I would use it alongside a budget, not instead of one.
The second is speed versus deliberation. A quick application can be valuable during an urgent situation, but urgency can also make people skim. I would deliberately slow down at the final review stage. The most important information is not how quickly the request begins; it is how the repayment fits with everything else scheduled to leave the account.
The third is access versus habit formation. A single advance may prevent a late bill or expensive alternative. Repeated advances can become part of the monthly routine, especially when the app is easy to open and the process feels less intimidating than a traditional loan. I would track every use in a simple note or budget category. If the same expense appears repeatedly, the pattern deserves attention.
There is also a psychological trade-off. “No interest” sounds reassuring, but it can lower the perceived cost of borrowing. I found it more responsible to replace the question “How much can I get?” with “How much can I repay without creating another gap?” That change in wording keeps the app in its proper role.
Another limitation is that the app cannot predict personal emergencies, changes in income, or other withdrawals from an account. Even a carefully planned repayment can become difficult if circumstances change. I would keep a small buffer whenever possible and avoid using every available dollar to cover the advance. A plan that works only under perfect conditions is not a strong plan.
Who is likely to gain the most
Gerald is most useful to people who have a stable near-term repayment source, need a relatively small bridge, and want to avoid interest-bearing borrowing. It may appeal to users who find traditional loan applications too heavy for a short timing problem, or to those who do not want a credit check to be the center of the process.
It is less appropriate for anyone seeking long-term debt relief, credit repair, a detailed money-management suite, or a substitute for emergency savings. It is also a poor fit for someone who already relies on advances every pay cycle. In that situation, the better next step is to examine fixed expenses, contact bill providers about hardship options, or seek trustworthy financial counseling.
The app’s broad Android compatibility is convenient for people who do not own a recent phone, and the Everyone rating makes its basic presentation accessible. Its free installation also makes it easy to explore. Even so, I would judge it by the complete request and repayment experience, not by installation cost or popularity alone. Around 4.2 thousand written reviews and its strong average rating suggest that many users find value in it, but personal financial circumstances still matter more than public sentiment.
After using it as a focused cash-flow option, my opinion is positive but deliberately cautious. The no-credit-check, no-interest approach addresses a real problem: a short gap between an obligation and incoming money. That is a meaningful advantage over costly alternatives when used carefully. The app does not remove financial risk, and it should never be treated as spare income.
My recommendation is to use Gerald only with a written repayment plan and a specific essential purpose. If those two conditions are present, it can be a practical bridge. If they are missing, a slower solution—saving, negotiating the bill, or choosing a broader financial product—will usually be healthier. For the right user, this app is useful because it stays focused; for the wrong user, that same simplicity can make borrowing feel easier than it should.
4.4
4.23K Reviews
Pros
- Simple application process with minimal paperwork
- Useful for covering unexpected short-term expenses
- Clear repayment details before accepting an advance
- Mobile access makes managing requests convenient
- May help users with limited traditional credit options
Cons
- Cash advances can carry high fees or borrowing costs
- Repayment may be required quickly after receiving funds
- Eligibility and availability can vary by state
- Late repayment could lead to additional charges
- Not suitable as a long-term solution for recurring expenses


